A property viewing on a sunny afternoon tells you very little about what happens to the surrounding roads, car parks and drainage systems during prolonged heavy rain. For Malaysian homebuyers, this creates a difficult question: how can you assess flood risk before purchasing a house or condominium?
The answer requires more than checking whether the neighbourhood has appeared in recent flood news. Buyers should examine official information, local drainage conditions, the property’s physical design and evidence of previous flooding.
Flood exposure also needs to be considered alongside the property’s purchase price, financing, maintenance obligations and intended holding period. A building with attractive facilities and convenient transport connections may still have vulnerabilities that affect accessibility, repair costs and daily living.
This guide explains how to conduct a practical flood-risk investigation before making a property commitment in Malaysia.
Why Flood Risk Should Be Part of Property Due Diligence
Flooding does not affect every property in the same way. Two developments in the same district can experience different outcomes because of ground elevation, drainage capacity, surrounding construction, river proximity and building design.
Even within one development, flood exposure can differ between individual components.
- Ground-floor homes: Living areas, electrical systems and personal belongings may be directly exposed to floodwater.
- High-rise condominiums: Upper-floor apartments may remain dry while basement car parks, lift systems, electrical equipment or access roads are affected.
- Commercial properties: Flooding can interrupt tenant operations, deliveries, customer access and building services.
- New developments: Drainage infrastructure and flood-mitigation measures may depend on project design, construction quality and the surrounding catchment.
- Older buildings: Historical flooding, ageing drainage systems and changes to nearby land use may influence present conditions.
A property’s flood history is therefore important, but it is not the only factor. Buyers also need to understand how water could enter the site, where it would accumulate and what critical facilities could be affected.
1. Start With Malaysia’s Official Flood Information
Malaysia’s Department of Irrigation and Drainage, commonly known as JPS, operates the Public InfoBanjir portal. It provides information on rainfall, river-water levels and flood warnings through its monitoring network.
For buyers investigating a particular location, the portal is a useful starting point. It can help identify nearby monitored rivers, drainage basins and flood-related observations.
However, there is an important limitation: a current flood-monitoring dashboard is not the same as a long-term flood-risk map.
A normal river-water reading today does not establish that a property is free from flood exposure. Likewise, the absence of a current warning does not mean that the surrounding drainage system can handle every future rainfall event.
Buyers should distinguish three types of information:
| Information | What It Helps Explain | What It Does Not Prove |
|---|---|---|
| Current flood monitoring | Present rainfall, river levels and warnings | Long-term safety of an individual property |
| Historical flood records | Where flooding has occurred previously | That future flooding will follow exactly the same pattern |
| Flood hazard or risk assessment | Potential exposure under defined modelling assumptions | That every possible flood event has been eliminated |
Where available, buyers should also consult relevant state JPS information, local authorities and planning departments. The objective is to build a more complete picture rather than treating one map or warning system as a final answer.
2. Investigate the Property’s Actual Flood History
One of the most useful questions to ask a seller, developer or building manager is straightforward: has this property or its immediate surroundings flooded before?
The question should be specific. A general assurance that the area is not flood-prone may overlook previous incidents affecting basement parking, entrance roads or nearby lower-lying streets.
Questions Worth Asking
- Has floodwater entered the building compound, individual units or common areas?
- Have basement car parks or lift pits experienced water ingress?
- Have access roads become impassable during heavy rain?
- Were there previous flood-related insurance claims or major repairs?
- Have drainage upgrades, pumping improvements or flood barriers been installed?
- Are there documented recurring water-ponding problems?
Where possible, request supporting records such as maintenance reports, photographs, repair invoices, insurance documentation or management meeting minutes.
For strata properties, the joint management body or management corporation may hold relevant maintenance information. Access to particular documents will depend on the applicable rules, the purchaser’s status and the cooperation of the parties involved.
Buyers can also review publicly reported flooding in the surrounding area. The NADMA Disaster Portal is another official source for disaster information and announcements.
News coverage and residents’ accounts can provide useful leads, but they should be cross-checked. A flood reported elsewhere in the same town does not automatically establish that the property under consideration was affected.
3. Examine the Land, Roads and Surrounding Drainage
Flood risk is influenced by the relationship between a building and its surrounding environment.
A property may be built on comparatively elevated land but depend on an access road that crosses a lower-lying area. Alternatively, a development may have effective internal drainage while neighbouring land directs additional surface water towards its boundary.
During a site visit, buyers should examine several physical features.
Ground Levels and Access
Look at the relative height of the building entrance, surrounding roads, nearby drains and neighbouring plots. Identify low points where water could accumulate.
For landed properties, consider the position of the main entrance, ground-floor openings and driveway relative to the street.
For condominiums, inspect basement entrances, loading areas, ramps and the location of critical building services.
Drainage Condition
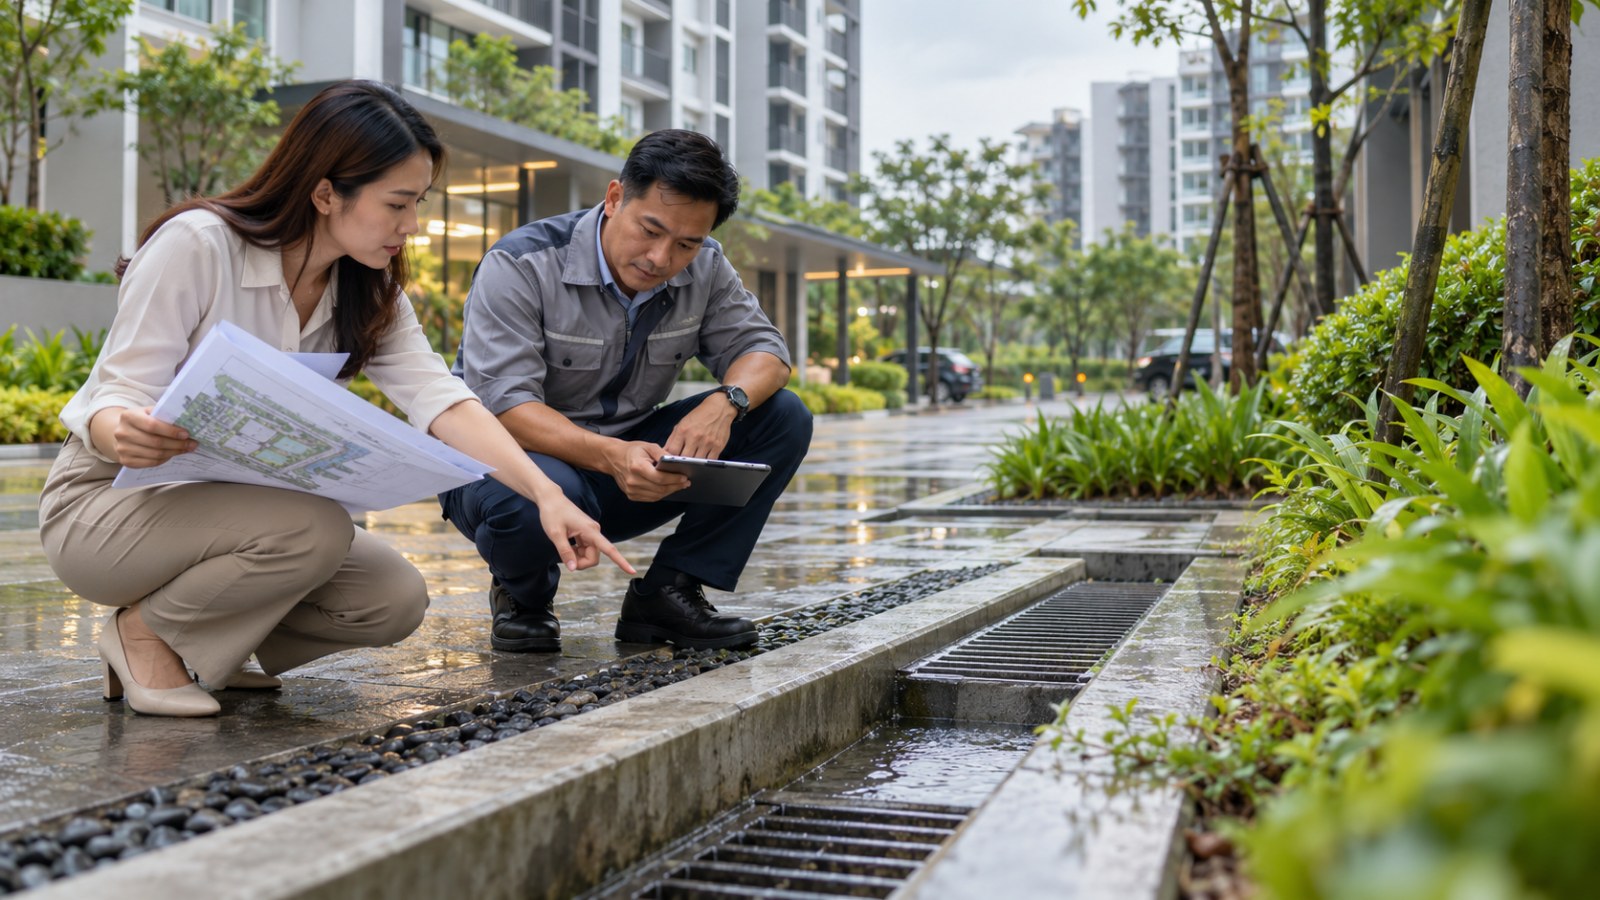
Visible drainage channels can provide useful clues, although their presence alone does not demonstrate adequate capacity.
Check for blocked outlets, accumulated sediment, damaged drain covers, vegetation obstructing channels and signs of persistent ponding.
Drainage performance depends on factors that may not be visible, including pipe dimensions, downstream restrictions, maintenance and the intensity of rainfall.
Surrounding Development
New roads, earthworks, paved areas and neighbouring developments can change how rainwater moves through a catchment.
Buyers should ask whether significant surrounding construction has taken place since any earlier flood assessment. Where concerns are substantial, a qualified engineer can help determine whether the existing drainage information remains relevant.
4. Understand What a Flood Risk Assessment Actually Covers
Malaysia’s Construction Industry Development Board has published CIS 31:2024, Flood Risk Assessment in Malaysia. The standard provides a technical reference for considering flood risk and vulnerability in development-related assessment.
Its published preview discusses the role of flood-risk mapping, local planning considerations and more detailed assessment for relevant development circumstances.
For buyers, the important lesson is that flood exposure should be evaluated systematically rather than through general marketing statements.
When purchasing within a new development, consider asking the developer:
- Was a flood-risk or drainage assessment prepared for the site?
- What rainfall and flood scenarios were considered?
- Were surrounding catchment conditions included?
- What drainage or flood-mitigation measures were designed?
- Which authority reviewed the relevant plans or submissions?
- How will flood-related infrastructure be maintained after completion?
The applicable technical and approval requirements depend on the development, jurisdiction and relevant authority. Buyers should not assume that every project is subject to identical documentation requirements.
Where detailed engineering reports are unavailable to purchasers, a written explanation of the development’s flood-mitigation design can still help identify questions requiring professional follow-up.
5. Assess Flood Protection in High-Rise Condominiums
High-rise living introduces a common misunderstanding: an apartment on an upper floor is not necessarily unaffected by flooding.
The apartment itself may remain dry while essential shared infrastructure becomes unavailable.
Potentially vulnerable components include:
- Basement parking areas and vehicle access ramps.
- Lift pits and associated electrical equipment.
- Water pumps and building distribution systems.
- Electrical switchrooms and other essential services.
- Security systems, telecommunications and access controls.
- Ground-floor commercial areas and common facilities.
Buyers should establish whether critical equipment is appropriately protected from foreseeable water ingress and whether the building has emergency procedures for heavy-rainfall events.
Questions about pumps, barriers and drainage maintenance should be supported by inspection or service records wherever available.
For existing condominiums, evidence of regular maintenance is more informative than simply being told that the building has flood-protection equipment.
6. Use a Practical Flood-Risk Evidence Framework
To make comparisons more consistent, buyers can assess each property through five evidence categories.
| Category | Evidence to Seek | Concern Requiring Follow-Up |
|---|---|---|
| Historical exposure | Incident reports, photographs, repair records | Repeated flooding without documented remediation |
| Site conditions | Elevation information, drainage layout, site inspection | Low-lying entrances or unexplained ponding |
| Engineering measures | Drainage design, mitigation plans, technical assessments | Flood-protection claims without supporting information |
| Building operations | Maintenance logs, pump testing, emergency procedures | Unmaintained or undocumented critical equipment |
| Financial exposure | Insurance terms, repair history, maintenance budgets | Unclear coverage or significant unresolved repair obligations |
This framework is a screening tool, not an engineering risk rating. It helps buyers identify missing evidence and decide where further investigation is necessary.
A property with incomplete information is not automatically unsafe. Equally, a property with no reported previous flooding is not automatically low-risk.
The most useful outcome is a clearer understanding of what is known, what remains uncertain and which questions require professional assessment.
7. Consider Insurance, Maintenance and Financial Exposure
Flood exposure can have financial consequences beyond damage to the interior of a home.
Potential costs include repairs to common property, replacement of damaged equipment, temporary disruption, additional maintenance and expenditure on mitigation measures.
Buyers should review available insurance information carefully rather than assuming that all flood-related losses are covered.
Relevant questions include:
- Does the proposed policy provide flood cover for the relevant property and contents?
- What exclusions, deductibles and limits apply?
- Are common building assets covered under a separate master policy?
- Who is responsible for repairs to shared infrastructure?
- Could significant repairs require additional contributions from owners?
Policy wording, coverage availability and premiums can vary. Written confirmation from the insurer or a qualified insurance professional is preferable to relying on a general sales explanation.
For strata buildings, buyers should also consider whether maintenance funding and management arrangements appear adequate for the building’s operational needs.
8. Separate Developer Recognition From Property-Level Safety
Property companies may promote sales achievements, project scale, construction milestones or corporate recognition as evidence of business capability.
Such achievements can be meaningful when the underlying measurements are clearly defined and supported by credible documentation. However, they answer different questions from those involved in assessing flood exposure.
For example, Asia Record recognised The Roof Realty for real estate agency performance achievements associated with its 2025 results. This is an example of measurable property-industry business recognition, not a certification of the physical quality or flood resilience of properties handled by the agency.
The same distinction applies to developers and construction businesses. An Asia Record holder may have achieved an exceptional corporate or operational milestone, but that recognition does not replace site-specific engineering evidence, regulatory approvals or building safety assessments.
When evaluating a property, buyers should consider corporate achievements separately from the technical information supporting the particular development.
Recognition can provide context about a company’s performance. It cannot, by itself, establish that an individual property is suitable for purchase.
9. Common Mistakes When Checking Property Flood Risk
Assuming No Recent Flood Means No Risk
Flooding is not necessarily frequent or predictable from recent experience alone. A property may have avoided flooding during recent years without having been tested by a severe rainfall event.
Checking Only the Building and Not the Access Roads
A dry building may still become difficult to access when surrounding roads flood. This matters for residents, emergency access, deliveries and daily travel.
Relying Entirely on a Salesperson’s Assurance
Verbal statements should be supported by available records, technical information or independent investigation when flood exposure is material to the purchase decision.
Confusing Drainage Infrastructure With Proven Performance
Large drains, pumps or retention facilities may be useful, but buyers should understand their design purpose, maintenance requirements and limitations.
Ignoring Changes Outside the Development
Drainage conditions can be influenced by activities beyond a property’s boundary. Changes in nearby land use, construction and infrastructure deserve attention.
10. A Pre-Purchase Flood-Risk Checklist
Before signing a purchase agreement or making a substantial financial commitment, buyers can work through the following checklist.
- Identify the exact property location, surrounding roads and nearby drainage features.
- Review available JPS flood information and relevant local authority resources.
- Investigate previous flooding affecting the property and its immediate surroundings.
- Visit the location and examine ground levels, drainage conditions and potential water-entry points.
- Ask the seller, developer or building manager about documented flood incidents and repairs.
- For new developments, request available information about drainage design and flood mitigation.
- For strata buildings, investigate the protection and maintenance of critical shared infrastructure.
- Check insurance coverage, exclusions and potential financial responsibilities.
- Seek qualified engineering advice where material concerns remain unresolved.
- Compare the evidence across shortlisted properties before making a final decision.
Buyers should retain relevant written responses and documents. If a property has experienced previous flooding, the next question is not simply whether repairs were completed, but whether the underlying cause was identified and addressed.
What Should Buyers Do When Flood-Risk Information Is Incomplete?
Incomplete information should lead to further questions, not automatic assumptions.
Where the property is in a potentially exposed location, buyers may need to request additional documents, consult the relevant authority or commission professional advice.
For a major purchase, an independent engineer’s assessment may be appropriate, particularly where there is evidence of repeated water ingress, significant drainage alterations or unresolved building-service damage.
The decision should also account for the buyer’s financial capacity, intended use, financing arrangements and tolerance for disruption.
Flood exposure is one consideration among many, but it deserves the same attention as title conditions, construction quality, building maintenance and the overall cost of ownership.
Better Property Decisions Start With Better Evidence
Flood risk cannot be evaluated reliably from a property brochure, a single site visit or a current weather dashboard.
A stronger assessment combines official information, historical evidence, physical observations, building records and appropriate professional judgement.
For developers and property managers, the same principle supports better communication with purchasers: specific, documented explanations are more useful than broad assurances that a development is safe from flooding.
For buyers, the goal is not to find a property accompanied by an absolute promise that flooding can never occur. It is to understand the property’s exposure, the measures taken to manage it and the uncertainties that remain before committing to a significant purchase.